DFAN14A: Additional definitive proxy soliciting materials filed by non-management and Rule 14(a)(12) material
Published on
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
SCHEDULE 14A
(Rule 14a-101)
INFORMATION REQUIRED IN PROXY STATEMENT
SCHEDULE 14A INFORMATION
Proxy Statement Pursuant to Section 14(a) of the Securities Exchange Act of 1934
(Amendment No. )
Filed by the Registrant ☐
Filed by a Party other than the Registrant ☒
Check the appropriate box:
| ☐ | Preliminary Proxy Statement |
| ☐ | Confidential, for Use of the Commission Only (as permitted by Rule 14a-6(e)(2)) |
| ☐ | Definitive Proxy Statement |
| ☒ | Definitive Additional Materials |
| ☐ | Soliciting Material Under § 240.14a-12 |
ETHAN ALLEN INTERIORS INC. |
(Name of Registrant as Specified In Its Charter) |
DGB Investment, Inc. Douglas Bergeron Qualified Personal Residence Trust Bergeron Nieces and Nephews Trust DOUGLAS G. BERGERON Anna Brockway Kristine E. Miller Stephen Oblak Stefanie Tsen Ward Jennifer m. harrison |
(Name of Person(s) Filing Proxy Statement, if other than the Registrant) |
Payment of Filing Fee (Check all boxes that apply):
| ☒ | No fee required |
| ☐ | Fee paid previously with preliminary materials |
| ☐ | Fee computed on table in exhibit required by Item 25(b) per Exchange Act Rules 14a-6(i)(1) and 0-11 |
DGB Investment, Inc. (“DGB Investment”), Douglas G. Bergeron and the other participants named herein (collectively, “DGB”) have filed a definitive proxy statement and accompanying WHITE universal proxy card with the Securities and Exchange Commission to be used to solicit votes for the election of its slate of highly qualified director nominees at the 2026 annual meeting of stockholders of Ethan Allen Interiors Inc., a Delaware corporation.
Item 1: On October 26, 2026, DGB issued the following press release:
Leading Independent Proxy Advisory Firm Glass Lewis Recommends Ethan Allen Shareholders Vote the WHITE Proxy Card “FOR” All Five of Doug Bergeron’s Director Nominees
Recommends Shareholders “WITHHOLD” Votes from All Five Incumbent Directors
More Than a Decade After Supporting the Board in 2015, Glass Lewis Cites Persistent Underperformance, Unfulfilled Promises of Growth, and Failures of Board Oversight
Endorses Mr. Bergeron’s Nominees and Their Clear Plan to Restore Shareholder Value, Concluding That Maintaining the Status Quo Poses Greater Risk to the Company
Mr. Bergeron Urges Shareholders to Follow Glass Lewis’ and Egan-Jones’ Recommendations and Vote the WHITE Proxy Card “FOR” ALL Five of His Nominees
PARK CITY, Utah--(BUSINESS WIRE)--Doug Bergeron, a significant shareholder of Ethan Allen Interiors Inc. (“Ethan Allen” or the “Company”) (NYSE: ETD) with beneficial ownership, collectively with his affiliates and associates, of approximately 5.2% of Ethan Allen’s outstanding common stock, today announced that leading independent proxy advisory firm Glass, Lewis & Co. (“Glass Lewis”) has recommended that Ethan Allen shareholders vote on the WHITE universal proxy card “FOR” ALL FIVE of his highly qualified director nominees to the Board of Directors (the “Board”) – Douglas G. Bergeron, Anna Brockway, Kristine E. Miller, Steve Oblak, and Stefanie Tsen Ward – at the Company’s 2026 Annual Meeting of Stockholders (the “Annual Meeting”) on November 4, 2026.
Glass Lewis recommended that shareholders “WITHHOLD” votes from all five incumbent directors, including Chairman and Chief Executive Officer M. Farooq Kathwari. The recommendation follows Egan-Jones Proxy Services’ (“Egan-Jones”) endorsement of Mr. Bergeron’s five director nominees and its recommendation to withhold votes from each incumbent director.
Mr. Bergeron commented, “Glass Lewis carefully weighed the potential paths forward and concluded that the greatest risk to Ethan Allen is leaving it in the hands of the incumbent directors. We agree. Glass Lewis’ recommendation is a resounding indictment of the incumbent Board – thoroughly dismantling the Board’s attempted defenses to our campaign – and serves as powerful validation of our case for change. After more than a decade of declining performance, broken promises, and failed oversight, Glass Lewis has concluded that the status quo is no longer defensible.
“With both Glass Lewis and Egan-Jones recommending that shareholders elect all five of our highly qualified nominees, the message is clear: Ethan Allen needs comprehensive Board change now. On November 4, shareholders have an opportunity to turn the page on years of underperformance and absent accountability by electing a new Board with the expertise and urgency required to renew this American icon. We urge shareholders to follow the recommendations of Glass Lewis and Egan-Jones and vote FOR all five of our nominees on the WHITE universal proxy card.”
In commenting on Ethan Allen’s persistent underperformance, unfulfilled promises of growth, selective disclosures, and failures of Board oversight, Glass Lewis stated:*
| · | “Ethan Allen is, by most relevant standards, a short-, mid- and long-term underperformer, with incumbent management and the board overseeing near-continuous structural regression and what appears to be an increasingly risky capital program, in all cases despite regular promises of imminent yields and attractive value.” |
| · | “It should be noted similar pledges underscored the board’s 2015 campaign defense, leading us to conclude at that time that representatives of Ethan Allen should be afforded more time to capture accelerated growth and improved performance. While acknowledging a limited overlap of continuing incumbent directors since that time, more than ten years on, and with persistently worst-in-class growth and materially substandard returns on the books, the returns are in.” |
| · | “In sum, the board effectively asks investors to discard the exceptionally evident in favor of the speciously selective, focusing on tightly framed metrics and targeted performance windows in a curated bid to hold the line. Tactical efficacy proves limited, as the preponderance of factors comprehensively establishes that Ethan Allen is in persistent operational decline, amplified by the long-term prioritization of cash distributions over durable growth.” |
| · | “Against a relatively imbalanced quantitative backdrop, management and the board had an opportunity to shift the narrative by disclosing 1Q results in advance of the meeting… With strategic and operational credibility on the line, updated metrics demonstrating even incipient success would be a boon. Instead, the board is necessarily fighting the impression that it is furtively punting on disclosure which may be damaging to its case.” |
| · | “In particular, and in apparent lieu of more rigid oversight on behalf of Ethan Allen’s unaffiliated investors, multiple notionally independent members of the sitting board communicated exceptional deference to Mr. Kathwari, which, in light of the Company’s observed performance and returns, undermines the notion that strategic and financial ownership and effective stewardship are front and center here.” |
In commenting on the strength of Mr. Bergeron’s nominees, their credible plan to restore shareholder value, and the compelling case for comprehensive Board change, Glass Lewis noted:*
| · | “In review of available materials, it appears challenging to suggest DGB fails to meet the brief. In particular, while the Dissident is seeking a full board spill, available materials afford EAI investors a comprehensive, top-down strategic, financial and corporate governance agenda coupled with a 100-day plan and a mid-term operating bridge.” |
| · | “With regard to DGB’s candidates, the slate appears compelling relative to the status quo… These skill sets appear to speak directly to the very issues with which the current board seems to struggle, and reasonably portend a more rigorous assessment of value-maximizing alternatives prospectively available to Ethan Allen.” |
| · | “Furthermore, observing that DGB’s nominees will, if elected, necessarily require time to verify and potentially revise central assumptions prior to the finalization of key strategic and financial initiatives is less a decisive counter than an observation of fundamental campaign strictures. Shareholders should reasonably anticipate that a reconstituted board, whether minority, majority or full, would take the time to thoughtfully and thoroughly assess the most appropriate course of action based on comprehensive data and associated diligence.” |
| · | “…DGB appears to have offered investors a credible and reasonably robust strategic and financial agenda alongside an alternate slate more evidently prepared to address muted accountability, operational backsliding and sputtering shareholder value. In view of these considerations, and in the absence of additional material developments, there exists suitable cause for investors to endorse material board refreshment at this time.” |
| · | “…the greater risk at this time appears to be entrusting critical oversight responsibilities to a board that has consistently failed to deliver on matters of operational accountability, shareholder value and executive succession across a disconcertingly wide range of reference periods, strategic narratives and tactical agendas.” |
Additional materials related to Mr. Bergeron’s campaign, including video interviews with his five director candidates, may be found at www.EthanAllenGrowth.com. Shareholders are encouraged to follow the campaign’s LinkedIn and X pages to stay informed in real time.
PROTECT YOUR INVESTMENT. RENEW AN AMERICAN ICON. VOTE FOR ALL FIVE DGB NOMINEES ON THE WHITE UNIVERSAL PROXY CARD TODAY
Shareholders with questions on how to vote their shares may visit www.EthanAllenGrowth.com/How-To-Vote.
*DGB has neither sought nor obtained the consent of Glass Lewis to use previously published information in this press release.
ADDITIONAL INFORMATION
DGB Investment, Inc. and Douglas G. Bergeron, together with the other participants in their solicitation (collectively, “DGB”), have filed a definitive proxy statement and accompanying WHITE universal proxy card with the Securities and Exchange Commission (“SEC”) to be used to solicit proxies with respect to the election of DGB’s slate of highly qualified director candidates and the other proposals to be presented at the 2026 annual meeting of stockholders (the “Annual Meeting”) of Ethan Allen Interiors Inc., a Delaware corporation (the “Company”). Stockholders are advised to read the proxy statement and any other documents related to the solicitation of stockholders of the Company in connection with the Annual Meeting because they contain important information, including information relating to the participants in DGB’s proxy solicitation. These materials and other materials filed by DGB with the SEC in connection with the solicitation of proxies are available at no charge on the SEC’s website at http://www.sec.gov. The definitive proxy statement and other relevant documents filed by DGB with the SEC are also available, without charge, by directing a request to DGB’s proxy solicitor, Okapi Partners LLC, at its toll-free number (877) 285-5990 or via email at info@okapipartners.com.
Contacts
Media Contact:
DGB@gasthalter.com
Investor Contact:
Bruce Goldfarb / Chuck Garske
Okapi Partners
(877) 285-5990
info@okapipartners.com
Item 2: Also on October 26, 2026, DGB sent an email to subscribers of www.EthanAllenGrowth.com, which is included below:
Leading Independent Proxy Advisory Firm Glass Lewis Recommends Ethan Allen Shareholders Vote the WHITE Proxy Card “FOR” All Five of Doug Bergeron’s Director Nominees
Recommends Shareholders “WITHHOLD” Votes from All Five Incumbent Directors
More Than a Decade After Supporting the Board in 2015, Glass Lewis Cites Persistent Underperformance, Unfulfilled Promises of Growth, and Failures of Board Oversight
Endorses Mr. Bergeron’s Nominees and Their Clear Plan to Restore Shareholder Value, Concluding That Maintaining the Status Quo Poses Greater Risk to the Company
Mr. Bergeron Urges Shareholders to Follow Glass Lewis’ and Egan-Jones’ Recommendations and Vote the WHITE Proxy Card “FOR” ALL Five of His Nominees
PARK CITY, Utah--(BUSINESS WIRE)--Doug Bergeron, a significant shareholder of Ethan Allen Interiors Inc. (“Ethan Allen” or the “Company”) (NYSE: ETD) with beneficial ownership, collectively with his affiliates and associates, of approximately 5.2% of Ethan Allen’s outstanding common stock, today announced that leading independent proxy advisory firm Glass, Lewis & Co. (“Glass Lewis”) has recommended that Ethan Allen shareholders vote on the WHITE universal proxy card “FOR” ALL FIVE of his highly qualified director nominees to the Board of Directors (the “Board”) – Douglas G. Bergeron, Anna Brockway, Kristine E. Miller, Steve Oblak, and Stefanie Tsen Ward – at the Company’s 2026 Annual Meeting of Stockholders (the “Annual Meeting”) on November 4, 2026.
Glass Lewis recommended that shareholders “WITHHOLD” votes from all five incumbent directors, including Chairman and Chief Executive Officer M. Farooq Kathwari. The recommendation follows Egan-Jones Proxy Services’ (“Egan-Jones”) endorsement of Mr. Bergeron’s five director nominees and its recommendation to withhold votes from each incumbent director.
Mr. Bergeron commented, “Glass Lewis carefully weighed the potential paths forward and concluded that the greatest risk to Ethan Allen is leaving it in the hands of the incumbent directors. We agree. Glass Lewis’ recommendation is a resounding indictment of the incumbent Board – thoroughly dismantling the Board’s attempted defenses to our campaign – and serves as powerful validation of our case for change. After more than a decade of declining performance, broken promises, and failed oversight, Glass Lewis has concluded that the status quo is no longer defensible.
“With both Glass Lewis and Egan-Jones recommending that shareholders elect all five of our highly qualified nominees, the message is clear: Ethan Allen needs comprehensive Board change now. On November 4, shareholders have an opportunity to turn the page on years of underperformance and absent accountability by electing a new Board with the expertise and urgency required to renew this American icon. We urge shareholders to follow the recommendations of Glass Lewis and Egan-Jones and vote FOR all five of our nominees on the WHITE universal proxy card.”
In commenting on Ethan Allen’s persistent underperformance, unfulfilled promises of growth, selective disclosures, and failures of Board oversight, Glass Lewis stated:*
| · | “Ethan Allen is, by most relevant standards, a short-, mid- and long-term underperformer, with incumbent management and the board overseeing near-continuous structural regression and what appears to be an increasingly risky capital program, in all cases despite regular promises of imminent yields and attractive value.” |
| · | “It should be noted similar pledges underscored the board’s 2015 campaign defense, leading us to conclude at that time that representatives of Ethan Allen should be afforded more time to capture accelerated growth and improved performance. While acknowledging a limited overlap of continuing incumbent directors since that time, more than ten years on, and with persistently worst-in-class growth and materially substandard returns on the books, the returns are in.” |
| · | “In sum, the board effectively asks investors to discard the exceptionally evident in favor of the speciously selective, focusing on tightly framed metrics and targeted performance windows in a curated bid to hold the line. Tactical efficacy proves limited, as the preponderance of factors comprehensively establishes that Ethan Allen is in persistent operational decline, amplified by the long-term prioritization of cash distributions over durable growth.” |
| · | “Against a relatively imbalanced quantitative backdrop, management and the board had an opportunity to shift the narrative by disclosing 1Q results in advance of the meeting… With strategic and operational credibility on the line, updated metrics demonstrating even incipient success would be a boon. Instead, the board is necessarily fighting the impression that it is furtively punting on disclosure which may be damaging to its case.” |
| · | “In particular, and in apparent lieu of more rigid oversight on behalf of Ethan Allen’s unaffiliated investors, multiple notionally independent members of the sitting board communicated exceptional deference to Mr. Kathwari, which, in light of the Company’s observed performance and returns, undermines the notion that strategic and financial ownership and effective stewardship are front and center here.” |
In commenting on the strength of Mr. Bergeron’s nominees, their credible plan to restore shareholder value, and the compelling case for comprehensive Board change, Glass Lewis noted:*
| · | “In review of available materials, it appears challenging to suggest DGB fails to meet the brief. In particular, while the Dissident is seeking a full board spill, available materials afford EAI investors a comprehensive, top-down strategic, financial and corporate governance agenda coupled with a 100-day plan and a mid-term operating bridge.” |
| · | “With regard to DGB’s candidates, the slate appears compelling relative to the status quo… These skill sets appear to speak directly to the very issues with which the current board seems to struggle, and reasonably portend a more rigorous assessment of value-maximizing alternatives prospectively available to Ethan Allen.” |
| · | “Furthermore, observing that DGB’s nominees will, if elected, necessarily require time to verify and potentially revise central assumptions prior to the finalization of key strategic and financial initiatives is less a decisive counter than an observation of fundamental campaign strictures. Shareholders should reasonably anticipate that a reconstituted board, whether minority, majority or full, would take the time to thoughtfully and thoroughly assess the most appropriate course of action based on comprehensive data and associated diligence.” |
| · | “…DGB appears to have offered investors a credible and reasonably robust strategic and financial agenda alongside an alternate slate more evidently prepared to address muted accountability, operational backsliding and sputtering shareholder value. In view of these considerations, and in the absence of additional material developments, there exists suitable cause for investors to endorse material board refreshment at this time.” |
| · | “…the greater risk at this time appears to be entrusting critical oversight responsibilities to a board that has consistently failed to deliver on matters of operational accountability, shareholder value and executive succession across a disconcertingly wide range of reference periods, strategic narratives and tactical agendas.” |
Additional materials related to Mr. Bergeron’s campaign, including video interviews with his five director candidates, may be found at www.EthanAllenGrowth.com. Shareholders are encouraged to follow the campaign’s LinkedIn and X pages to stay informed in real time.
PROTECT YOUR INVESTMENT. RENEW AN AMERICAN ICON. VOTE FOR ALL FIVE DGB NOMINEES ON THE WHITE UNIVERSAL PROXY CARD TODAY
Shareholders with questions on how to vote their shares may visit www.EthanAllenGrowth.com/How-To-Vote.
*DGB has neither sought nor obtained the consent of Glass Lewis to use previously published information in this press release.
ADDITIONAL INFORMATION
DGB Investment, Inc. and Douglas G. Bergeron, together with the other participants in their solicitation (collectively, “DGB”), have filed a definitive proxy statement and accompanying WHITE universal proxy card with the Securities and Exchange Commission (“SEC”) to be used to solicit proxies with respect to the election of DGB’s slate of highly qualified director candidates and the other proposals to be presented at the 2026 annual meeting of stockholders (the “Annual Meeting”) of Ethan Allen Interiors Inc., a Delaware corporation (the “Company”). Stockholders are advised to read the proxy statement and any other documents related to the solicitation of stockholders of the Company in connection with the Annual Meeting because they contain important information, including information relating to the participants in DGB’s proxy solicitation. These materials and other materials filed by DGB with the SEC in connection with the solicitation of proxies are available at no charge on the SEC’s website at http://www.sec.gov. The definitive proxy statement and other relevant documents filed by DGB with the SEC are also available, without charge, by directing a request to DGB’s proxy solicitor, Okapi Partners LLC, at its toll-free number (877) 285-5990 or via email at info@okapipartners.com.
Contacts
Media Contact:
DGB@gasthalter.com
Investor Contact:
Bruce Goldfarb / Chuck Garske
Okapi Partners
(877) 285-5990
info@okapipartners.com
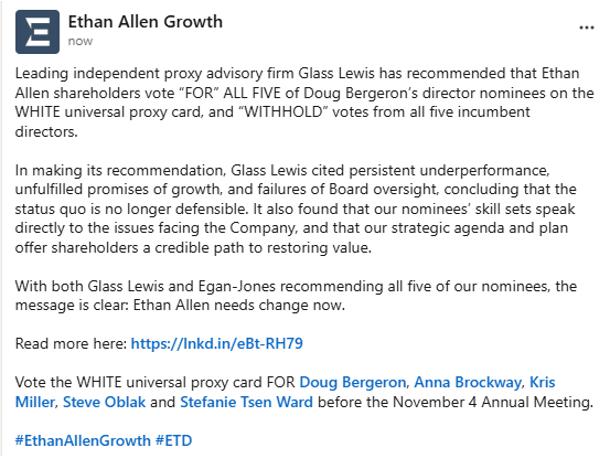
Item 3: Also on October 26, 2026, DGB posted the following materials on LinkedIn and X.com:
Item 4: Also on October 26, 2026, DGB posted the following material to www.EthanAllenGrowth.com: